The Threshold Clause: Turnover Rents and the New Arithmetic of Bond Street Leases
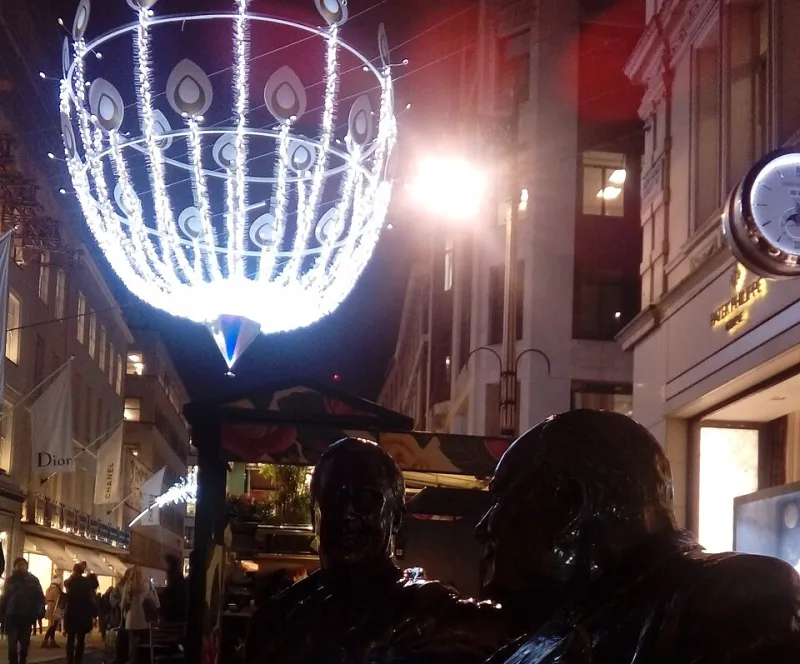
Photo: VirtuallyLondonBecky, CC0, via Wikimedia Commons
For much of the past two decades, the Bond Street lease was a study in certainty. A fixed base rent, agreed after lengthy negotiation, rose on review and formed the bedrock of institutional valuations. Turnover rents were a provincial curiosity, or a concession reserved for the most temporary of pop-ups. In 2026, that assumption is being quietly dismantled. Sales-linked rent structures are no longer an exception on Bond Street; they are becoming part of the standard vocabulary of negotiation, particularly where luxury tenants and their advisers are pushing for greater alignment between occupancy cost and trading performance.
Why the Fixed-Rent Model Is Under Strain
The case for revisiting the fixed-rent orthodoxy rests on a simple observation: the trading environment has become less predictable. Tourist flows, the redistribution of luxury spending across London’s retail villages, the persistent influence of online channels and the uneven recovery of international footfall have combined to make a single, inflexible rent figure feel increasingly anachronistic. Tenants facing volatile sales want a lease that shares some of that volatility. Landlords, meanwhile, have watched incentive packages and void periods erode the effective income of fixed-rent deals. A turnover lease offers a different bargain: a lower base rent in exchange for a share of the upside.
The result is not a wholesale replacement of the fixed-rent lease. It is a rebalancing. On Bond Street, the most sophisticated negotiations now begin with a conversation about the occupancy cost ratio—rent and service charge as a proportion of sales—rather than a straightforward quoting rent. That shift in starting point is significant. It moves the discussion from what the market will bear to what the store can sustain.
The Anatomy of a Turnover Clause
A turnover lease is deceptively simple in outline and highly technical in practice. The core components are familiar: a base rent, a threshold or breakpoint, and a percentage of sales above that threshold. But the detail determines who carries which risk. The base rent is typically set below open-market levels—sometimes materially so—to reflect the tenant’s exposure to the turnover component. The threshold may be a natural breakpoint, calculated by dividing the base rent by an agreed percentage, or a negotiated figure that reflects the store’s historical or projected sales.
The percentage itself varies. For luxury fashion and jewellery, where gross margins are high but sales volumes are sensitive to product cycles and tourism, the turnover percentage might sit in the mid-single digits. For categories with lower margins or higher space requirements, the figure can rise. Caps and collars are increasingly common: a cap protects the tenant from excessive payments in a boom year, while a collar ensures the landlord receives a minimum return even if sales disappoint. These mechanisms add complexity, but they also make the structure bankable.
The definition of gross sales is where many negotiations founder. What counts? Online sales fulfilled from the store? Click-and-collect returns? Wholesale transactions? VAT? The treatment of each must be agreed in advance, and the answers can move the effective rent by double-digit percentages. On Bond Street, where omnichannel strategies blur the boundary between physical and digital, this is not a technical afterthought. It is the main event.
Data, Audit and the Trust Deficit
Turnover rents require data. Landlords need to verify sales figures, and tenants need confidence that their commercially sensitive information is protected. The result is a new layer of lease machinery: monthly reporting obligations, EPOS integration, third-party monitoring arrangements and audit rights. Each of these provisions carries cost and friction. Tenants, particularly luxury brands with global reporting systems, often resist full transparency. Landlords, mindful of valuation requirements, need assurance that the figures are accurate and complete.
The compromise is usually a tiered approach. Headline sales data is shared monthly; detailed audit rights are triggered only if reported figures fall outside an agreed band; and confidentiality provisions restrict the circulation of tenant data to the landlord’s professional advisers. Even so, the trust deficit is real. Turnover leases work best where there is a history of cooperation and a shared interest in the store’s success. On Bond Street, where many tenant-landlord relationships are long-standing, that foundation often exists. In more transactional corners of the market, it is harder to build.
Landlord Appetite: Risk, Reward and the Capital Value Question
Landlords have not embraced turnover rents out of altruism. The appeal is a combination of income resilience and tenant retention. A lower base rent reduces the risk of default and vacancy, while the turnover component offers a call option on the store’s performance. In a market where rental growth has been hard to come by, that optionality has value.
But the capital value consequences are not straightforward. Valuers and lenders treat base rent and turnover rent differently. Base rent is capitalised at a lower yield; turnover rent, being variable, is often capitalised at a higher yield or given limited weight in the valuation. For an institutional investor, a lease with a substantial turnover component may produce a lower headline valuation than an equivalent fixed-rent lease, even if the expected total income is similar. That creates a tension between asset management and valuation. Landlords who can demonstrate a strong track record of turnover receipts—and who can persuade valuers to recognise that record—are better placed to narrow the gap.
The Tenant Perspective: Sharing the Upside, Hedging the Downside
For luxury tenants, the attraction is control over occupancy cost. A turnover lease allows a brand to invest in fit-out, staffing and stock without committing to a fixed rent that may become burdensome if trading softens. It also aligns the lease with the realities of a multi-channel business, where sales can migrate between store, website and wholesale channels with little warning. The trade-off is transparency. Tenants must accept a degree of financial disclosure that some brands find uncomfortable.
The most sophisticated tenants are now negotiating thresholds that reflect their own sales forecasts rather than the landlord’s. They are also pushing for greater flexibility on the definition of gross sales, particularly where online returns and cross-channel fulfilment are concerned. The outcome is a lease that looks less like a standard institutional product and more like a bespoke partnership agreement.
What It Means for Investment Strategy
For investors, the rise of turnover rents on Bond Street has three implications. First, asset management capability matters more than ever. A turnover lease is not a passive instrument; it requires active monitoring, regular reconciliation and a willingness to engage with tenants on trading performance. Second, lease complexity increases valuation uncertainty. Portfolios with a mix of fixed and turnover leases will need to be underwritten with greater care, and lenders will demand more detailed information. Third, the model rewards patience. Landlords who accept a lower base rent in exchange for a share of future growth are making a bet on Bond Street’s enduring appeal as a luxury destination.
That bet is not without risk. The turnover lease is not a solution to weak demand; it is a mechanism for sharing the consequences of demand. But in a market where certainty is scarce, sharing has its attractions. The threshold clause, once a footnote in the lease, is now a headline item in the negotiation. The language of Bond Street rents has been rewired, and the investment case is being rewritten alongside it.