The Programme Premium: Why Time-to-Trade Now Prices Bond Street
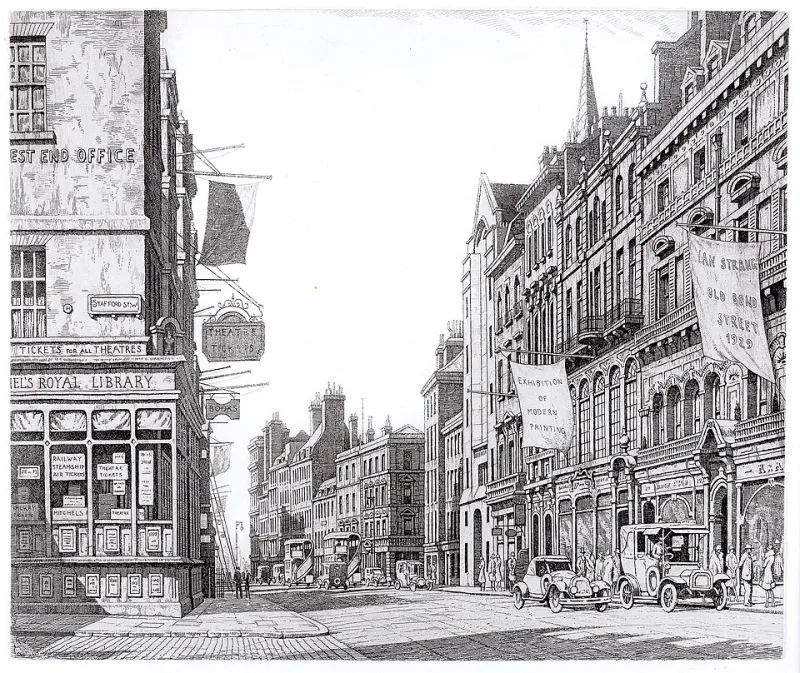
Photo: Ian Strang, Public domain, via Wikimedia Commons
On Bond Street, the most closely scrutinised document in a letting negotiation is no longer always the rent schedule. Increasingly, it is the contractor's programme. For brands considering a flagship or a compact boutique on the street, the difference between a unit that can be handed over in March and one that may not be available until September is no longer an administrative detail. It is a commercial term, and one that landlords are beginning to price.
From Rent-Free to Time-Free
The orthodox currency of a Bond Street letting has long been the rent-free period and the capital contribution. Those instruments remain important, but they address occupancy cost. They do not address the cost of delay. A tenant that signs in January but cannot trade until the autumn carries rent, rates, insurance and staffing costs without revenue, and may miss a seasonal trading window altogether. In a market where flagship space is expected to perform as a media asset as much as a shop, a lost launch season is a lost marketing moment.
That is why the negotiation has shifted towards time. Landlords who can offer a credible trading date — supported by completed landlord works, agreed shopfront details and a pre-booked contractor slot — are finding that certainty commands a premium. It may not appear as a higher headline rent. It often appears as a firmer rent, a shorter incentive package or a better covenant.
The Scarcity of the Right Diary
Bond Street's built fabric explains much of the constraint. Many buildings sit within a conservation area, and a significant number carry listed status. Shopfront alterations, signage, stonework repairs, mechanical and electrical upgrades and fire strategy works all require careful coordination with Westminster City Council's planning and conservation officers. Approval timetables are not always within a landlord's control, and conditional consents can add weeks to a programme that was already tight.
At the same time, the pool of contractors with genuine experience of the street is limited. Specialist joinery, stone restoration, façade work and the integration of modern building services into historic structures demand a particular skill set. The best firms are booked well in advance, and a missed diary slot can push a handover into the next quarter. For a tenant with a fixed launch date, that risk is material. It is also increasingly visible to landlords, who understand that a vacant unit with a delayed programme is a vacant unit with a delayed income stream.
What Landlords Are Actually Offering
The response has been a quiet re-engineering of the landlord's package. Rather than simply offering a longer rent-free period to compensate for uncertainty, some owners are offering a form of delivery certainty. That can take several forms: early access licences that allow the tenant's contractors to begin enabling works before the formal lease commencement; phased possession, with the tenant fitting out upper floors while ground-floor landlord works are completed; pre-approved shopfront and signage designs, reducing the scope for late-stage planning friction; and landlord-appointed contractors who are already familiar with the building's quirks.
A smaller but growing category is the ready-to-trade unit. These are spaces where the landlord has completed the shell, services and compliance works to a specification that allows a tenant to move directly to its own fit-out without waiting for base-build completion. The rent may be higher than for a raw shell, but the time-to-trade is shorter and more predictable. For a brand under pressure to open before a peak trading period, that trade-off can be decisive.
The Valuation Effect
From an investment perspective, the significance is straightforward. Delivery certainty shortens the void, brings forward rent commencement and reduces the period in which a landlord carries empty-building costs. It also lowers the risk of a tenant failing to complete its fit-out on schedule, which in turn reduces the probability of a disputed rent start date or a renegotiation.
Assets that can demonstrate a reliable route from agreement for lease to trading are therefore likely to be viewed more favourably by purchasers. The market has spent several years focusing on carbon risk, service charges and tenant covenant strength. Time-to-income is emerging alongside those factors as a valuation input. A building with a proven delivery record, pre-agreed landlord works and a credible contractor framework is, in effect, a lower-risk income stream than one where every letting restarts the same programme uncertainty.
That does not mean every landlord should rush to pre-complete every unit. Over-specification can be expensive and may not suit a tenant's brand requirements. The value lies in removing the landlord-controlled risks, not in designing the tenant's shop. The most effective approach is usually a well-defined landlord shell, a transparent programme and a clear allocation of responsibility for the works that sit between shell and trading.
The Contractual Fine Print
As delivery certainty becomes a selling point, it also needs to be documented. Heads of terms are beginning to include long-stop dates for landlord works, programme warranties where appropriate, and agreed extensions of time for heritage or planning consents. Early access licences require careful drafting on insurance, service charge and liability. Contractor novation arrangements, if used, need to be clear about design responsibility and latent defects.
Tenants, for their part, should test the credibility of any promised date. A programme that assumes immediate conservation consent or an available specialist contractor is not a programme; it is an aspiration. The prudent approach is to ask for evidence of past delivery, to understand the dependencies, and to build in realistic contingency without creating an incentive for delay.
The Risk of Over-Promising
The obvious danger is that delivery certainty becomes a marketing claim rather than an operational reality. Landlord works can slip. Contractor availability can tighten. Cost inflation can force value engineering. If a promised handover date is missed, the goodwill generated by the offer can evaporate quickly, and the tenant may seek relief through rent abatement or other remedies.
The landlords who get this right tend to be those who treat the programme as seriously as the rent. They appoint contractors early, secure consents before marketing the unit, and communicate slippage promptly. They also recognise that a slightly later but reliable date is worth more to a tenant than an ambitious date that cannot be met.
The New Negotiating Table
For Bond Street, the implication is that the letting conversation now has two centres of gravity: price and programme. The first is familiar. The second is becoming a differentiator. In a street where flagship space is scarce and brand competition is intense, the ability to guarantee a trading date is a form of landlord performance that tenants will pay for — whether through a smaller incentive, a firmer rent or a longer commitment.
As 2026 progresses, the contractors' diaries will remain tight and heritage approvals will remain a fact of life. The landlords who plan around those constraints, rather than negotiating after them, will be the ones who convert space into income most efficiently. On Bond Street, time is no longer simply money. It is a lease term.