Marketing Budgets in Brick: The Unit Economics of Bond Street's Online-Born Tenants
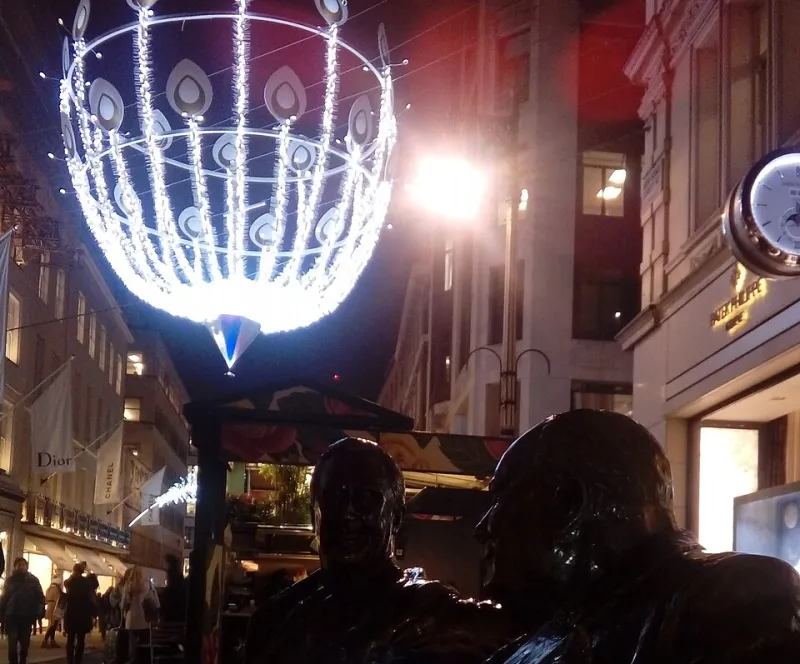
Photo: VirtuallyLondonBecky, CC0, via Wikimedia Commons
For a certain kind of tenant, the question is no longer how much stock the ground floor can hold, but how many appointments it can host. On the Mayfair edge of Bond Street, a 1,100 sq ft unit that once carried a jewellery display now opens by booking only, its fit-out closer to a private client salon than a shop. The brand behind it was built online, spends most of its marketing budget on paid social, and treats the address as the most expensive — and most credible — line in its acquisition stack.
That is the shift now being priced into a small but growing slice of prime ground-floor demand. Digital-first luxury brands — fragrance, skincare, eyewear, jewellery, made-to-order apparel — are taking modest, design-led spaces on Bond Street and its quieter approaches, not to trade in the traditional sense but to convert. The unit economics are different, and so are the leases, the fit-outs and the landlord calculations that sit behind them.
From Sales Density to Acquisition Cost
Traditional luxury underwriting begins with sales per square foot. A Bond Street ground floor is valued on what it can turn over, and rents have historically been set against that benchmark. Online-born tenants invert the logic. For them, rent is a marketing cost, compared with the blended cost of acquiring a customer through digital channels. If a 1,000 sq ft unit costs £800,000 a year in rent and associated occupation costs, and the brand expects to convert 2,000 high-value clients through the door at an average first-order value of £600, the arithmetic can look competitive against a paid-media budget that might otherwise absorb the same sum at a higher cost per acquisition.
That does not make Bond Street cheap. It makes it legible in a different currency. The brands taking these units are not comparing themselves with Hermès or Chanel on sales density; they are comparing the address with a year of performance marketing. The comparison is imperfect — attribution is difficult, halo effects are real — but it is the one now being made in boardrooms from Shoreditch to Stockholm.
The Lease as a Media Buy
The lease structures reflect that framing. Where a legacy luxury house might sign a fifteen-year term with a mid-term uplift, the digital-native tenant typically seeks three to five years, with a tenant-only break at year two or three. Turnover rents, once the preserve of outlet and fringe locations, are appearing more often in Mayfair, usually as a topping-up mechanism above a base rent that is set below the quoting level.
Landlords have become more willing to entertain those terms where the alternative is a longer void. Westminster City Council's stance on change of use and the practicalities of fitting out a listed building on Bond Street mean that a quick, well-capitalised entrant can be more attractive than a protracted negotiation with a traditional retailer. The covenant is the sticking point. Many digital-first brands are privately held, thinly capitalised on paper and difficult to underwrite using conventional credit metrics. The result is a market in which rent deposits, parent-company guarantees and rent-frees are doing more work than headline rents.
Fit-Out: Less Stock, More Set
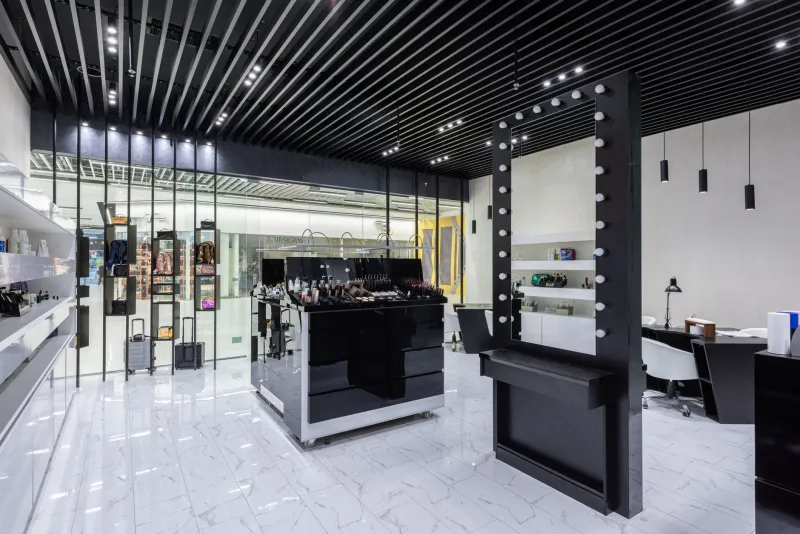
The physical requirements are distinctive. Stock density is low. A digital-native fragrance or skincare brand might hold fewer than 200 SKUs on the floor, with the bulk of inventory held centrally and shipped next day. What the unit needs instead is a residential quality of finish, private appointment rooms, good acoustics and enough electrical capacity to run diagnostic equipment, digital screens and a fitting suite.
Fit-out costs typically land below those of a traditional luxury flagship — perhaps £200 to £350 per square foot, against £500 or more for a jewellery or watch environment — but the design intensity is higher. These are spaces built to be photographed, and the return on that investment is measured in content as much as in transactions. Landlord contributions to fit-out are increasingly negotiated, particularly where the unit has been vacant for some time or sits on a secondary frontage.
What Landlords Want
For landlords, the appeal is diversification of income and tenant mix. A cluster of online-born brands can enliven a stretch of street that has lost a legacy anchor, and it can support the pitch to other tenants. The risk is correlation. If several of these occupiers are funded by the same venture cycle, a downturn in consumer tech valuations could translate into a cluster of break notices at once.
There is also the question of what happens to the unit if the brand retreats. A fit-out designed for appointments rather than footfall can be costly to re-let to a conventional retailer, and the landlord may inherit a space that needs stripping back. That asymmetry — flexible for the tenant, potentially awkward for the building — is now part of the negotiation.
The Durability Question
Is this a lasting source of demand or a cycle? The evidence is mixed. Comparable districts — Marylebone High Street, parts of Soho, Covent Garden — have seen online-born brands graduate from pop-ups to permanent stores, and some have stayed. Others have contracted back to digital-only once the acquisition maths changed. On Bond Street, the test will be whether the first wave renews beyond its initial break. A renewal is a more honest signal than an opening.
The early indications suggest that the strongest candidates are brands with a genuine product rationale for physical retail — fragrance, fit-critical apparel, eyewear, high-touch skincare — rather than those using space purely as a billboard. The latter tend to treat the lease as a campaign, and campaigns end.
What It Means for Value
For valuers and investors, the arrival of digital-first tenants complicates the comparables. A letting to an online-born brand at a lower headline rent but with a shorter term and a turnover top-up is not directly comparable to a fifteen-year institutional lease. The income is less durable, the re-letting risk is different, and the incentive package may be larger. That does not make it worse, but it makes it different, and the market is still working out how to price the difference.
The credibility address, in other words, is now a two-way proposition. The tenant borrows the street's authority; the street borrows the tenant's growth. Whether that exchange holds through the next cycle will depend less on the brands' marketing budgets than on the quality of the covenants behind them.