Doors Ajar, Windows Dark: A Frontage-Level Audit of Bond Street’s Vacant Units
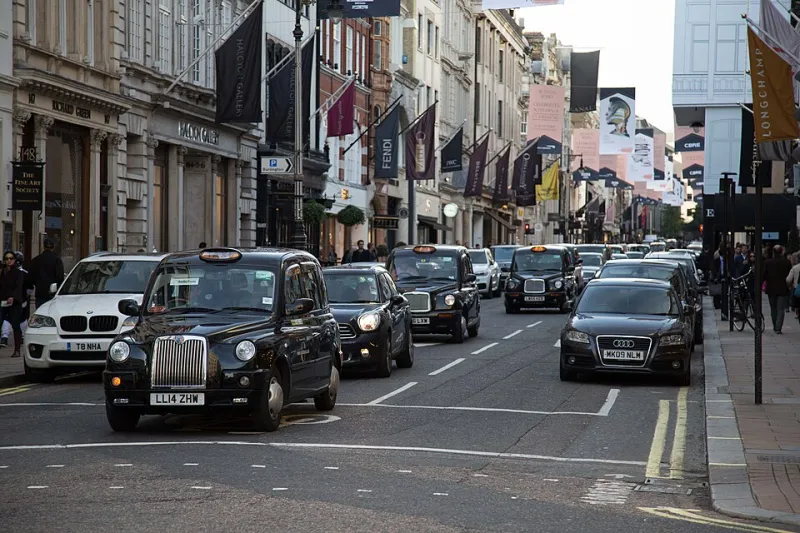
Photo: mazzon888, CC0, via Wikimedia Commons
At first glance, the numbers look uncomfortable. A walk of the Bond Street conservation area in early November 2026 finds just over two dozen ground-floor units without an open trading frontage. That is the figure that tends to enter the market narrative: a vacancy rate that appears to have risen, a sign of caution, a crack in prime. The figure is also misleading. A vacant window is not the same as a vacant unit, and an empty shop is not the same as an unwanted shop.
The Difference Between a Gap and a Void
One Bond Street’s frontage-level audit classifies every clear ground-floor vacancy on New Bond Street, Old Bond Street and the immediately adjoining streets — Brook Street, Maddox Street, Grafton Street and the lower reaches of Berkeley Square — by frontage width, approximate floorplate, lease status and visible works. The distinction that matters most is between a temporary gap and a structural void. A temporary gap has a programme: hoarding, a building notice, a fit-out contractor, a known incoming tenant or an agreed lease awaiting completion. A structural void has none of those things. It is marketed, or withdrawn from the market, with no visible works and no public evidence of a deal.
The difference is not academic. It determines whether a vacant window should be read as a symptom of weak demand or as a sign of landlord confidence. A unit under refurbishment is often a unit that has already been re-let, or is being prepared for a tenant with specific requirements. A unit standing empty with no works is a different proposition. It may be overpriced, poorly configured, compromised by access or simply waiting for a landlord who does not need to transact.
What the Frontage Ledger Shows
In our count, roughly half of the visible vacancies fall into the temporary category. Several are behind hoardings with planning or licensing notices; others show the tell-tale signs of a fit-out — protective film on glazing, temporary lighting, deliveries of fixtures. These are not evidence of a weak market. They are evidence of a market that is still moving, albeit more slowly than the headlines imply. The structural voids are fewer, but they are more revealing. They cluster in three places: narrow-frontage units where the display area is too shallow for a modern luxury format; upper-floor or basement-reliant units where the ground floor alone cannot carry the rent; and secondary positions where the footfall is good but not Bond Street good.
Frontage remains the first filter. A wide, regular frontage on the prime pitch can still command attention from international brands, even in a cautious market. A narrow frontage on a side street is a harder sell. The difference is not simply about visibility. It is about the cost of creating a statement. A brand that needs to install a full shopfront, a facade treatment and a usable internal staircase is underwriting a capital expenditure programme that must be justified by sales density. Where the frontage is compromised, the arithmetic becomes harder.
The Floorplate Trap
Floorplate is the second filter. Bond Street’s older buildings often offer irregular shapes, listed ceilings and constrained servicing. A unit that looks generous on a plan can be awkward in practice. The most difficult vacancies are those where the ground floor is small but the overall floorplate is large, leaving a tenant to pay for space that cannot be used for trading. These units tend to sit empty for longer, and they tend to attract incentive packages rather than headline rent growth.
That is where landlord pricing power is being tested. Owners with well-configured, wide-frontage assets are holding quoting rents and using rent-free periods, phased rents or capital contributions to close deals. Owners with compromised assets are discovering that the market will not pay for space it cannot use. The result is a two-tier letting market within a few hundred metres. The headline rent may look stable; the effective rent tells a different story.
Lease Status and the Price of Patience
Lease status is the third filter. A unit that is under offer is not the same as a unit that is available. A unit in legal hands is not the same as a unit that is being marketed. Our audit found that a meaningful share of the visible vacancies are already in negotiation or subject to agreed heads of terms. That does not mean the deals will complete, but it does mean the vacancy is not a pure demand signal. It is a timing signal.
The structural voids tell a simpler story. They are the units where the landlord has not yet adjusted expectations, or where the asset requires capital expenditure that the landlord is unwilling to commit. In a market where tenants are more selective, patience has a cost. Every month of void is a month of rates, insurance and service charge. The owner who waits for the perfect tenant may eventually get the rent, but the holding cost erodes the return.
Where the Next Re-rating Appears
The next re-rating is unlikely to appear on the prime pitch itself. It is more likely to emerge at the seams — the side streets where temporary gaps are resolving into new lettings, and the upper floors where residential or flexible commercial use is beginning to compete with retail. That is not a sign of decline. It is a sign of maturity. Bond Street is no longer a single market. It is a collection of micro-markets, each with its own frontage economics, floorplate constraints and lease dynamics.
For investors, the lesson is to count doors, not headlines. The vacancy rate is a blunt instrument. The frontage ledger is a sharper one. It shows where demand is still strong, where supply is genuinely constrained and where the next round of rental evidence is likely to be set. In late 2026, the empty windows of Bond Street are not a simple story of excess supply. They are a map of pricing power, and the map is more interesting than the headline.